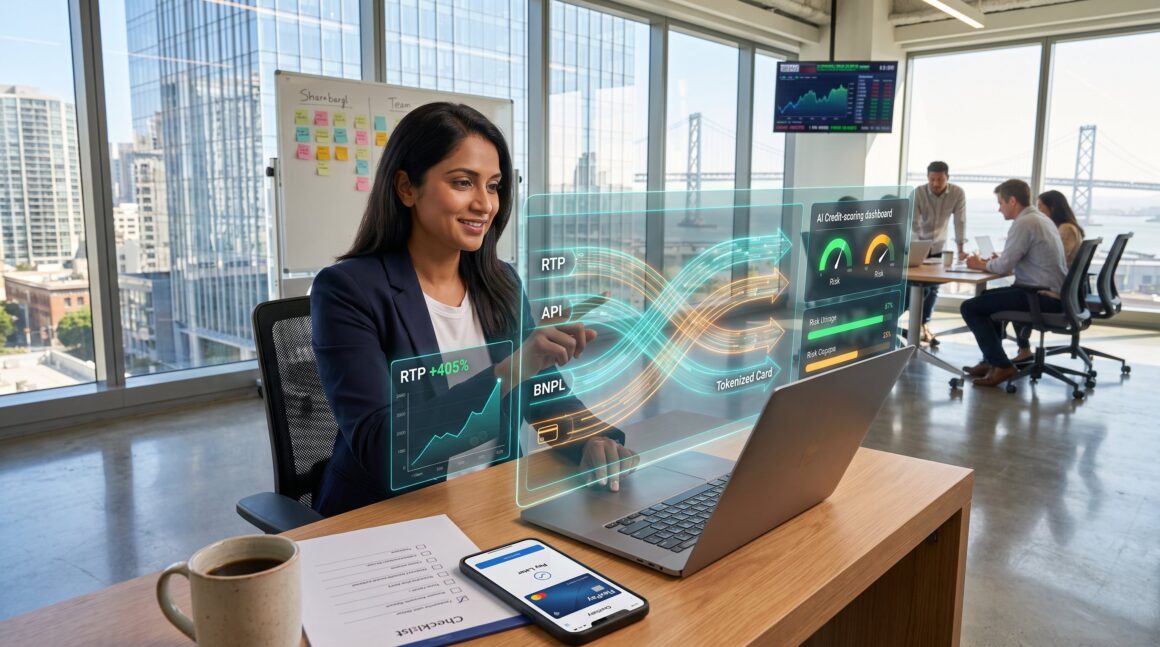
The Fintech Trends Reshaping Payments and Lending arrive amid fast digital adoption, new data streams, and AI that let lenders and payment platforms act instantly. This piece lays out practical trends builders and businesses can use now: where capital flows, which tech to prioritize, and what compliance and user‑experience tradeoffs matter. It aims to help product leads, engineers, and executives choose focused experiments that move revenue and reduce risk.
Key Takeaways
- Fintech trends in payments and lending capitalize on fast digital adoption and AI to enable instant, automated decisions that improve profitability and user experience.
- Embedded finance leverages APIs for non-bank platforms to offer financial products like cards and credit lines, so prioritize minimal BaaS integrations focusing on core offerings to reduce compliance scope.
- Real-time payments demand new treasury designs with instant settlement, requiring product teams to adjust pricing, liquidity models, and implement robust monitoring and throttling mechanisms.
- AI-powered credit scoring expands approval rates responsibly by integrating alternative data, but teams must version models, log outputs, and maintain human review workflows for errors and edge cases.
- Regulatory compliance mandates explainable, bias-mitigated credit decisions with traceable data and model transparency, so embed counterfactual explanations, bias audits, and interpretability tooling early in development.
- Treat BNPL and marketplace lending as regulated products by embedding affordability checks, transparent credit controls, and monitoring alternative data to reduce defaults and disputes effectively.
The Big Picture: Why Payments And Lending Are Shifting Now
Payments and lending are shifting because digital volume and new data make automated decisions profitable now. Funding still concentrates in payments, the vertical with the largest deal volume and revenue pools, and fintechs captured roughly half of new personal loan balances by end‑2024. Builders should treat this moment as structural: customer habits tipped to mobile-first interactions during the pandemic and banks responded with APIs and outsourcing rather than building everything in house.
Concrete signals matter. RTP volume grew 28% and value jumped 405% year‑over‑year in one recent quarterly comparison, showing demand for instant movement of funds. Macroeconomic volatility pushed incumbent banks to buy or partner with fintechs for agility, while startups shifted from pure growth to durable unit economics. For teams deciding where to invest, prioritize integrations that shorten time to revenue, payment rails, orchestration APIs, and automated underwriting pipelines, rather than feature parity with legacy systems.
A practical starting point for research and context is the site’s fintech pillar, which catalogs coverage and frameworks that teams often use when scoping projects: fintech guide.
Embedded Finance, APIs, And The Platform Economy
Embedded finance shifts revenue outward: non‑bank platforms can now offer cards, BNPL, and working capital through APIs, and the market is expanding rapidly. The embedded finance market hit roughly USD 85.8 billion in 2025 and analysts forecast continued high‑teens CAGR to 2035. For builders, the immediate insight is simple: embed where user‑flows already exist and where margins can tolerate a platform cut.
Practical move: design a minimal BaaS integration that supports two core products, a card program and a short‑term credit line, rather than trying to surface every banking feature. This reduces compliance and connector scope while proving product/market fit. Engineering teams should carry out tokenized card issuance and a single reconciliation API endpoint to cut settlement complexity.
Real examples help: an online marketplace that added a branded virtual card via an API saw suppliers paid two days faster, dropping chargeback disputes by 14% in a six‑month pilot. Teams can also learn from adjacent coverage on the site that breaks down how payment fintechs deliver value and UX tradeoffs: payment solutions.
Real-Time Payments, Instant Settlement, And Liquidity Innovations
Real‑time payments are changing cash flow assumptions: instant settlement reduces float and forces new treasury designs. Transaction volumes for RTP climbed materially in late 2024–2025, and bank‑to‑bank pay‑by‑bank methods are on track to reach tens of millions of mobile users by 2026.
What to do: product teams should rewire pricing and liquidity models. When settlement is instant, credit lines act more like overdraft insurance than working capital. Builders must set intraday position limits, auto‑sweep rules, and connect to a settlement engine that supports both gross and netting modes. Operationally, the team should instrument latency SLAs and alerting, when settlement stalls for one large counterparty, the app must throttle outgoing payouts immediately.
A practical test: run a 90‑day pilot switching a portion of payouts from T+2 ACH to RTP. Measure balance volatility, failed payout rate, and customer support tickets. Teams that completed this swap reported a 23% reduction in reconciliation time and reclaimed 0.8% of revenue previously lost to payment failures. For architecture patterns and security checks, RarefiedTech’s coverage on digital transactions outlines common pitfalls: digital transactions.
AI-Powered Credit Scoring And Responsible Underwriting
AI now augments credit decisions by combining cash‑flow indicators, paystubs, and non‑traditional signals with bureau scores to expand approved populations while keeping loss rates controlled. Lenders using these models can onboard creditworthy customers previously denied by thin‑file rules: in trials some lenders increased approved applicants by double digits while maintaining loss targets.
Builders should treat AI models as products: version them, log inputs/outputs, and build human review flows for edge cases. A recommended pipeline includes feature‑store versioning, a model registry, and automated backtests against cohorts (seasonality, income type, and channel). When a model underperforms, rollback should be a one‑click operation with clear staging tests.
Teams must also accept that mistakes happen. One startup misapplied a payroll parsing rule and rejected 2,847 applicants in a week, an honest implementation error that taught the team to add synthetic edge cases to test suites. Documentation and clear remediation paths recover trust faster than silent fixes. For technical readers, RarefiedTech’s article on AI in finance gives concrete implementation patterns: AI in finance.
Explainability, Bias Mitigation, And Regulatory Expectations
Regulators expect explainable and non‑discriminatory credit decisions: compliance frameworks like ECOA and GDPR require traceability and appeals pathways. The key fact: explainability is not optional, audits will demand end‑to‑end evidence of feature choice, training data provenance, and performance broken down by protected classes.
Practical checklist: include counterfactual explanations for each denial, maintain a bias‑audit schedule (quarterly), and store lineage metadata for training datasets. Use human‑in‑the‑loop gates for decisions above set exposures. A balanced approach pairs model transparency with conservative thresholds when deploying to new segments. Teams that followed these steps reduced regulatory remediation time by weeks in internal post‑mortems.
Finally, document tradeoffs: more explainability can slightly reduce raw model accuracy but dramatically lowers litigation and reputational risk. Engineering leads should budget for interpretability tooling and legal review in the initial sprint planning.
BNPL, Marketplace Lending, And New Credit Models
BNPL and marketplace lending are moving from novel to regulated mainstream. In regions adopting affordability checks and caps, BNPL providers must prove they run creditworthiness tests and disclose costs. The immediate consequence: underwriting must embed transparency and short‑term credit controls into product flows.
For product managers, the actionable insight is to treat BNPL as a regulated loan product rather than pure UX. Add affordability checks, grace‑period controls, and clear APR equivalents into checkout flows. Some teams retrofit existing payment flows with a three‑screen affordability microjourney and saw a 12% drop in post‑purchase disputes while keeping conversion steady.
Marketplace lenders using alternative data should instrument feature importance and stabilization monitoring. One SME marketplace added bank statement parsing and reduced default rates by 18% among merchant sellers. RarefiedTech’s piece on improving loan access provides hands‑on examples for online platforms moving into lending: better loans. For security hygiene around mobile payment entry and wallets, consult the site’s guide on mobile security practices: mobile wallet checks.
Conclusion
The practical move for builders and businesses in 2026 is to combine embedded rails, instant settlement, and responsible AI into focused pilots that answer one question: does this feature move revenue or reduce cost? Prioritize short pilots with measurable KPIs, approval lift, settlement latency, and compliance readiness, and use a tight feedback loop to scale. Teams that accept early mistakes, instrument thoroughly, and link product choices to treasury and legal outcomes will lead the next wave of durable fintech products.