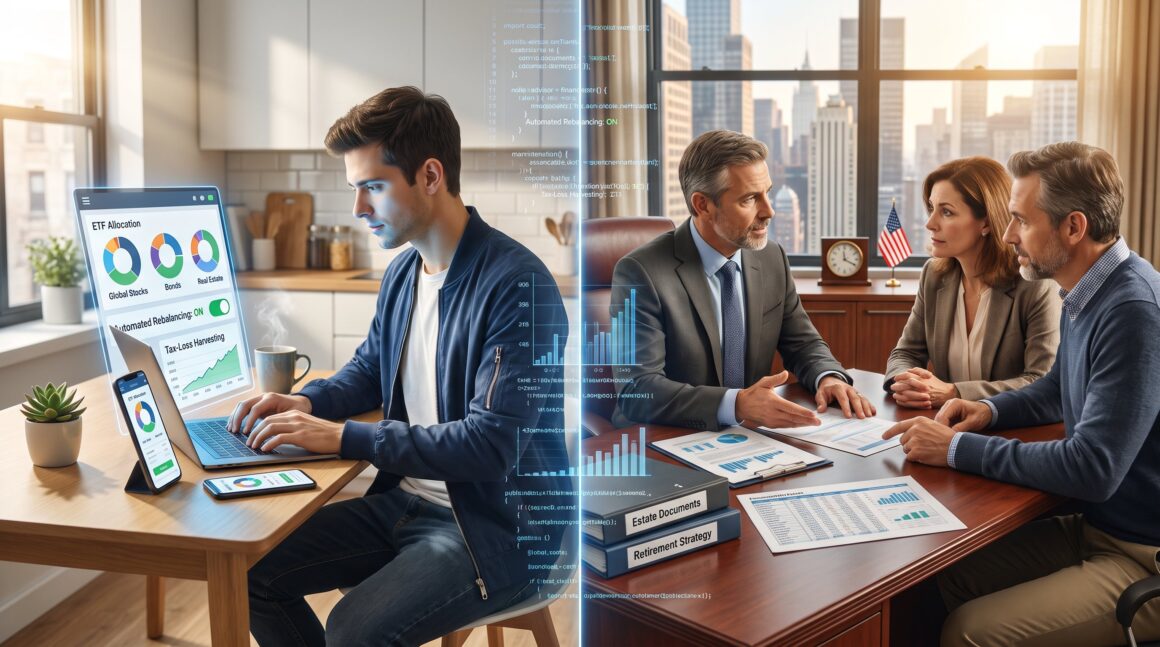
Robo-Advisors vs. Human Financial Advisers: Key Differences matter when someone decides where to park savings, plan retirement, or manage taxes in 2026. This piece explains how algorithm-driven platforms and traditional advisers operate, where each excels, and which choice fits particular financial goals. It focuses on concrete trade-offs, fees, service levels, and accessibility, so readers can decide with evidence rather than marketing claims.
Key Takeaways
- Robo-advisors use automated algorithms to manage portfolios with lower fees, making them ideal for simple investment goals and tight budgets.
- Human financial advisers provide personalized planning, behavioral coaching, and complex tax and estate strategies, benefiting clients with multifaceted financial situations.
- Both robo-advisors and human advisers offer similar long-term market exposure, but differ in service levels, risk management depth, and fee structures.
- Cost differences are significant: robo-advisors charge around 0.15%–0.50% AUM, while human advisers typically charge 0.50%–1.25% AUM, affecting net returns over time.
- A hybrid approach combines the cost efficiency of robo-advisors with periodic human consultations, adapting to growing financial complexity over time.
- Choosing between robo-advisors and human advisers depends on financial complexity, budget, and the need for personalized emotional support and planning guidance.
How Robo-Advisors And Human Advisers Work
Robo-advisors and human advisers start from the same aim, grow and protect assets, but they use different methods.
Robo-Advisors: Algorithms, Portfolios, And Automation
Robo-advisors use coded decision rules to build diversified portfolios, rebalance automatically, and apply features like tax-loss harvesting. The clear fact: software executes trades at scale. A user completes risk and goal questionnaires: the platform maps answers to model allocations and executes ETFs or index funds. Automation reduces manual steps and often lowers costs to roughly 0.15%–0.50% AUM. In practice, a robo platform might rebalance weekly and harvest losses across thousands of accounts, saving time and consistency compared with human scheduling. But, the system lacks discretionary judgment for rare events and personal nuances.
Human Advisers: Financial Planning, Personalization, And Behavioral Coaching
Humans add judgment and planning depth. The fact: advisers combine investment management with tax, estate, insurance, and retirement planning. A human adviser meets clients, uncovers life events, and adapts plans when income, health, or family status changes. They provide behavioral coaching during downturns, which can prevent costly panic selling. Human advice often costs 0.50%–1.25% AUM or a flat fee. For complex tax strategies, bespoke estate plans, or shifting career income, human oversight catches edge cases algorithms miss. Yet advisers can vary widely in approach and availability.
Head-To-Head Comparison: Performance, Risk Management, And Service Levels
Robo-advisors and human advisers achieve similar long-term market exposures but differ where nuance matters.
Performance: The core fact is that neither consistently outperforms the market after fees: differences emerge from implementation. Robo-advisors deliver low-cost, tax-aware ETFs and disciplined rebalancing. Human advisers sometimes add alpha through tactical allocation or tax planning, but their higher fees can erase those gains. Public comparisons generally show service differences more clearly than clear outperformance.
Risk management: Robo platforms control risk via diversification, automatic rebalancing, and algorithmic glide paths. Humans add qualitative risk checks: business ownership, concentrated stock positions, or illiquid assets. For example, an adviser might trim company stock exposure after a liquidity event, something a robo model would not detect unless the position fit standard inputs.
Service levels: Robo tools are standardized and available 24/7 online: service usually includes chat or periodic calls. Human advisers offer personalized reviews, goal refinement, and emotional support during crises. A client with $500,000 might get quarterly face-to-face reviews and bespoke tax coordination from a human, while a robo client receives online reports and automated tax-loss harvesting.
Costs, Fees, And Accessibility: What You Actually Pay
Cost differences are the clearest, most measurable distinction.
Fees: Robo-advisors commonly charge 0.15%–0.50% AUM: human advisers commonly charge 0.50%–1.25% AUM. The fact: on a $500,000 portfolio, a robo platform could cost about $1,250 per year while a human AUM adviser might cost $4,000–$5,000. Those numbers directly affect net returns over decades.
Minimums and accessibility: Robo platforms often accept accounts from $0 to $5,000, lowering the barrier for early savers. Human advisers frequently require higher minimum assets, though some firms and hybrid models serve smaller accounts.
Trade-offs: Lower fees buy scale and consistency: higher fees buy customization and human judgment. Someone with a simple 401(k) and basic goals can keep more returns by using a robo-advisor. Conversely, someone with multiple income streams, business equity, or complex estate needs usually benefits from human planning.
Contextual resources: For a broader view of fintech coverage that frames these differences, readers may refer to Fintech coverage.
When To Choose A Robo-Advisor, A Human Adviser, Or A Hybrid Approach
Choose based on complexity, budget, and behavioral needs.
Robo-advisor fits: The simple fact is that robo-advisors suit straightforward investing goals and tight budgets. Example: a 28-year-old contributor building a taxable index portfolio and retirement accounts will likely save thousands in fees using a robo platform and still receive automatic rebalancing and tax-loss harvesting.
Human adviser fits: The fact is that human advisers shine when finances include business equity, rental real estate, multiple tax jurisdictions, or inheritances. A couple planning a $3 million estate with complex beneficiary issues benefits from human coordination of tax, trust, and insurance planning.
Hybrid approach: Many platforms offer both automation and human access. The hybrid model combines low-cost portfolio management with periodic planner consultations. A common path: start with a robo solution during accumulation, then layer in human advice as net worth and life complexity increase.
Technology context: The industry evolution, where algorithms handle routine tasks and advisers tackle complex judgment, is explored in reporting on the wealth management transformation.
Conclusion
Robo-advisors reduce costs and standardize portfolio management: human advisers add planning depth and behavioral support. The right choice depends on the person’s finances, willingness to pay for customization, and need for emotional guidance. In practice, many find a staged approach, automation early, human oversight later, delivers the best mix of cost efficiency and tailored planning.