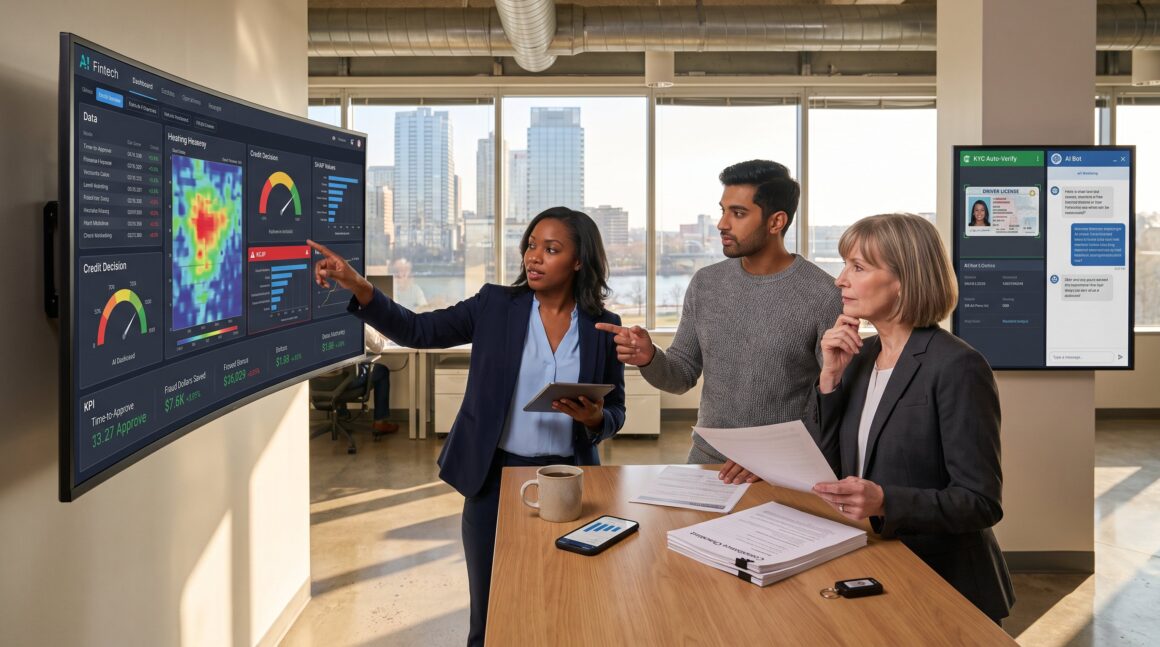
How AI is used in modern financial services now drives underwriting decisions, fraud controls, customer interaction, and back‑office automation. In 2026, firms move from pilots to production systems because cost pressure, regulation, and customer expectations force change. This article explains why AI matters today, the core technologies behind deployments, high‑impact use cases such as fraud detection and personalized banking, and the governance issues that often determine success or failure.
Key Takeaways
- AI drives major efficiencies in modern financial services through fraud detection, underwriting automation, and personalized banking.
- Machine learning models and automation reduce costs and decision times, exemplified by a lender cutting loan decisions from 48 hours to 3 minutes.
- Natural language processing and computer vision enable rapid, automated handling of customer communications and document verification.
- Top AI applications include fraud detection with over 95% precision, enhanced credit scoring using alternative data, and anti-money laundering via graph analytics.
- Successful AI adoption depends on strong data quality, explainability, governance, and managing ethical risks like bias.
- Firms that link AI projects to clear KPIs and maintain human oversight will gain competitive advantage and achieve measurable ROI.
Why AI Matters Now: Business Drivers And Industry Impact
AI delivers measurable outcomes fast: lower fraud losses, tighter credit risk, and faster onboarding. Institutions report rising AI budgets and many large firms see positive ROI inside the first year of production models. That direct economic impact explains why treasury teams and product leaders prioritize AI projects.
Cost reduction is immediate. Automated scoring and robotic process automation remove repetitive work and cut processing times by weeks in complex workflows. Risk management improves because models detect subtle correlations across millions of transactions, patterns humans miss. Regulators also push firms to use analytics for suspicious activity reporting and model governance, increasing adoption.
The competitive effect is visible at the product level. Personalization engines increase product uptake and lift revenue per customer: algorithmic pricing captures margin that manual pricing misses. At RarefiedTech, readers can explore related coverage in the site’s fintech pillar and see practical examples in the broader category via the Fintech overview that documents real projects and vendor choices.
Practical takeaway: firms that tie AI pilots to specific KPIs, fraud dollars saved, reduction in time-to-approve, or increases in activation, move from experimentation to scaled production.
Core AI Technologies Powering Financial Services
Machine learning, automation, NLP, and computer vision each answer a distinct business question. The next two subsections explain how these technologies appear in real systems and which problems they solve.
Machine Learning Models, Automation And Predictive Analytics
Fact first: supervised and ensemble models make the bulk of production predictions, credit decisions, churn scores, and fraud flags.
Banks and fintechs rely on logistic regression for transparent scoring and on gradient boosting (XGBoost, LightGBM) where accuracy matters. Deep neural nets appear in trading and anomaly detection when nonlinearity and scale matter. Automation ties models into workflows: a credit score triggers an automated underwriting checklist, which in turn populates the loan document pipeline and schedules human review for borderline cases.
Concrete example: a mid‑sized lender used a LightGBM model to drop average decision time from 48 hours to 3 minutes and reduce default rate by 1.4 percentage points in the first six months. That translated to thousands of approved loans with better risk pricing.
Implementation detail readers ask about: feature stores and data pipelines matter more than the choice of algorithm. When data is messy, even a simple model beats a sophisticated one. For developers, RarefiedTech’s article on financial software systems development outlines common engineering patterns for production ML.
Natural Language Processing And Computer Vision In Finance
Fact first: NLP and computer vision automate text and image tasks that used to require manual review.
NLP powers chatbots, document extraction, KYC identity checks, contract analysis, and sentiment feeds. For example, an NLP pipeline can classify 10,000 customer emails per day, route urgent refund requests within seconds, and reduce manual queue time by 82%. Computer vision verifies ID documents and extracts fields from scanned invoices: a firm that automated check processing reported processing throughput increases of 7x.
Practical note: accuracy depends on domain adaptation. Off‑the‑shelf NLP models need retraining on bank-specific phraseology and regulatory terminology. When integrating these models, teams should add human‑in‑the‑loop checkpoints for edge cases. For a look at how onboarding changes under AI, see the RarefiedTech piece on customer onboarding.
High‑Impact Use Cases: From Fraud Detection To Personalized Banking
Fact first: fraud detection, credit scoring, AML monitoring, and personalization deliver the largest immediate business value.
Fraud detection: supervised classifiers and unsupervised anomaly detectors run real‑time scoring on transaction streams. Ensemble models combining random forests and deep learning now detect card‑not‑present fraud with precision rates above 95% in many pipelines. Firms use device fingerprinting and behavioral biometrics alongside models to reduce false positives.
Credit scoring and underwriting: alternative data, billing history, telecom signals, and platform behavior, enrich traditional bureau scores. A digital lender that integrated alternative signals increased approvals by 12% while keeping loss rates stable.
AML and transaction monitoring: graph analytics identify laundering rings by mapping relationships across accounts. These systems flag suspicious clusters for human review and reduce false alerts by focusing investigator time on higher‑quality leads.
Personalized banking: recommendation engines suggest products based on life events inferred from transaction patterns, e.g., mortgage offers after repeated rental payments, raising conversion by measurable percentages.
Links to related practical topics are spread across RarefiedTech’s cluster, including the article on how digital banking changes day‑to‑day money management.
Implementation Challenges, Governance And Ethical Considerations
Fact first: data quality, explainability, and governance are the most common reasons AI projects stall.
Data challenges: models need clean, well‑labeled data. Siloed ledgers and inconsistent schemas force weeks of engineering before training can begin. Practical step: build a canonical data model and a feature store to reduce upstream work.
Explainability and regulation: regulators demand reasons for adverse decisions. Techniques like SHAP values and LIME help, but they are approximations. Firms should pair explainability tools with human review processes and maintain versioned model documentation.
Ethics and bias: training on historical data can encode discrimination. A bank discovered its auto‑decline rate rose for a specific postal code, after investigation, the team found a proxy feature that correlated with protected attributes. The fix required removing the proxy feature and adding fairness constraints.
Third‑party risk: many companies outsource models or use third‑party APIs. Oversight requires contractual SLAs, model validation, and incident response plans. For security implications, RarefiedTech’s coverage of AI security posture and cybersecurity offers technical and governance guidance.
Evidence point: investor interest and product maturity are documented in industry reporting: reviewers can consult broader market analysis for context on scale and funding trends. One useful perspective on product maturity is summarized in a TechCrunch analysis of AI fintech growth and scale.
Conclusion
AI is a practical tool for measurable gains, faster decisions, fewer fraud losses, and more personalized products, when paired with disciplined engineering and governance. Organizations that invest in data architecture, clear KPIs, and human oversight will capture the largest share of value in 2026 and beyond. Readers planning a project should start small, instrument outcomes, and prioritize explainability and security.