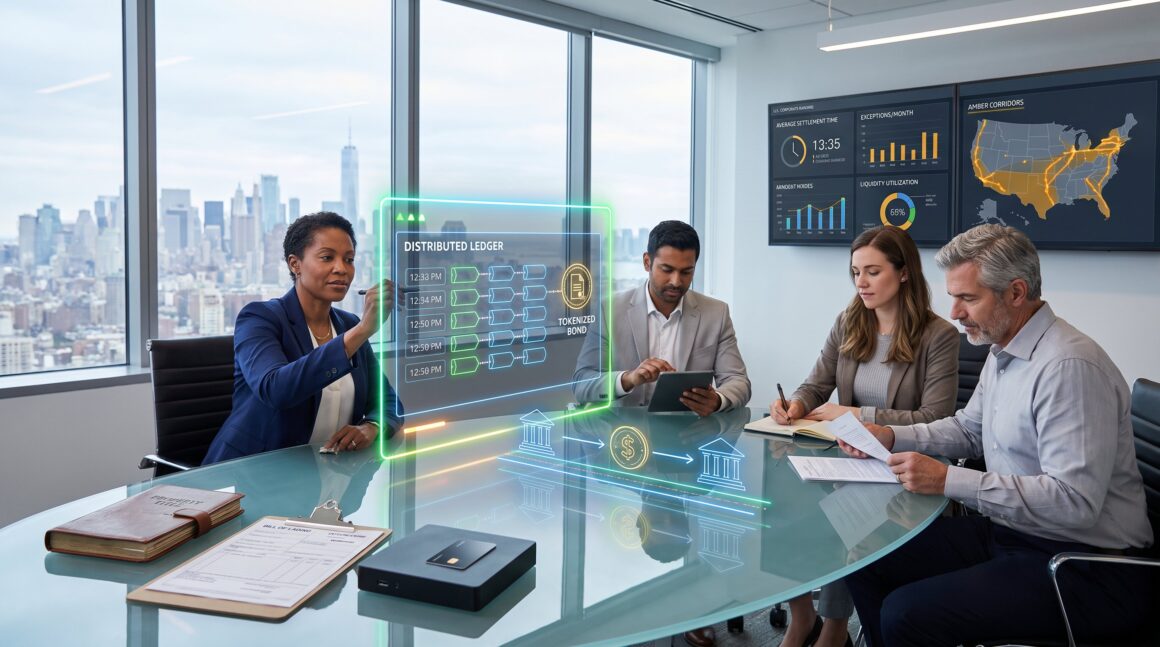
Blockchain Beyond Cryptocurrency: Practical Finance Applications are reshaping how banks move money, manage assets, and verify identity. In 2026, institutions treat distributed ledgers as infrastructure, not speculation. This article explains seven concrete finance uses, payments, tokenization, trade finance, identity, custody, market plumbing and consortia, that practitioners can evaluate and adopt today. It balances clear mechanics with real-world constraints so teams can decide which pilots to run, what operational risks to expect, and which regulatory checkpoints to include.
Key Takeaways
- Blockchain in finance provides a shared, auditable ledger that drastically reduces reconciliation time and operational risks.
- Cross-border payments benefit from blockchain by enabling near real-time settlements and lowering costs using tokenized deposits and stablecoins.
- Tokenization of assets like stocks, bonds, and real estate unlocks liquidity, allows fractional ownership, and reduces settlement costs by up to 40%.
- Regulatory compliance and secure custody are critical for on-chain assets; firms must ensure legal enforceability and robust custodial models.
- Trade finance and KYC automation via blockchain streamline processes, reduce fraud, and cut compliance duplication through shared identity attestations.
- Joining permissioned ledger consortia with clear governance and interoperability plans is essential for scalable and efficient blockchain adoption in finance.
How Blockchain Works In Finance — Core Concepts For Practitioners
Fact first: a shared ledger gives identical, time-stamped records to all permissioned participants, creating an auditable source of truth. That single sentence changes reconciliation from daily firefights to predictable, verifiable states.
Distributed ledger technology (DLT) in finance uses nodes run by banks, custodians, or infrastructure providers. Each node holds the same transaction history so one reconciliation error does not cascade. Smart contracts sit on top of those ledgers to automate conditional events, payment on delivery, automatic margin calls, or interest accruals. A practical example: a regional bank can cut end-of-day reconciliation from 12 hours to under 90 minutes by running a private ledger for inter-branch settlements.
Benefits are measurable: fewer intermediaries, lower settlement latency, and reduced counterparty risk. Downsides exist too, operational complexity, the need for deterministic contract code, and careful key management. Firms should pilot with narrow use cases (e.g., FOP payments or collateral movements) and instrument metrics: average settlement time, exceptions per month, and cost per transaction. These metrics allow teams to compare blockchain pilots to existing SWIFT or ACH baselines.
Cross-Border Payments And Real-Time Settlement
Fact first: blockchain enables near real-time cross-border payments by replacing correspondent chains with tokenized rails. That reduces latency and often lowers fees.
In practice, banks use stablecoins or tokenized deposits as on‑chain cash rails. A treasury desk can move tokenized deposits between two banks and achieve effective T+0 settlement rather than waiting for multi‑day correspondent flows. This matters when FX volatility costs a trading desk 0.2% per day: shaving two days saves real money. Emerging multibank networks now settle hundreds of millions in intraday flows, and pilot results show end-to-end latency cut by 70% in some corridors.
Real implementation needs operational controls: deterministic onboarding, dispute resolution paths, and liquidity management to avoid on-chain congestion. Integrating with existing payment engines and treasury systems is essential: several banks reuse existing reconciliation modules and add gateway adapters to the ledger. For teams wanting a strategic view, RarefiedTech’s Fintech coverage guide summarizes related projects and vendor approaches.
Tokenization Of Assets: Stocks, Bonds And Real Estate
Fact first: tokenization converts ownership rights into digital tokens, enabling fractional holdings and extended trading hours. That can unlock liquidity and broaden investor access.
Real examples already exist: institutions tokenize corporate bonds to permit T+0 or T+1 settlement, and property tokens let 1,000 investors own fractions of a rental building. Tokenized equity platforms show faster settlement and lower custody frictions because transfers occur on-chain. A practical metric: tokenized offerings can reduce settlement operational costs by an estimated 20–40% versus legacy clearing for certain instruments.
Large asset managers and banks are building catalogs of tokenized real‑world assets worth tens of billions, often pairing issuance with regulated custodians and automated corporate actions. Custody models evolve: qualified custodians combine cold-wallet protections with legal frameworks to hold tokens for institutions. Teams should plan for investor onboarding, secondary-market rules, and liquidity provisioning, since token markets can be thin without market‑making.
Regulatory, Custody, And Market Infrastructure Implications
Fact first: on‑chain assets must obey securities rules, AML/KYC, and data-privacy laws: compliance cannot be an afterthought.
Regulators require clear legal ownership, transferability rules, and investor protections for tokenized securities. Custodians face dual responsibilities: secure private keys and provide legal safekeeping. That led to acquisitions and partnerships in custody space: firms need robust proof-of-reserve processes and incident response plans. Market infrastructure must bridge tokens to existing CSDs and clearinghouses for systemic stability, many pilots integrate ledger records with traditional registrar systems so regulators see a single reconciled view.
For practitioners, immediate steps include legal opinions on token enforceability, choosing custodial models with insured custody, and running interoperability tests with central securities depositories. These precautions reduce regulatory pushback and increase institutional confidence in tokenized markets.
Trade Finance, Supply Chain Finance And KYC Automation
Fact first: digitizing letters of credit and KYC reduces processing time and fraud by layering verifiable events on a shared ledger.
In trade finance, replacing paper bills of lading with on-chain records means a seller receives automatic payment when a verified shipment event occurs. Banks report some pilots cut issuance and verification times from days to hours. For supply chain finance, visibility into upstream invoices enables dynamic discounting and lower financing costs for suppliers, one platform showed a 15% increase in early-pay uptake after ledger adoption.
KYC automation uses shared identity attestations. Once a corporate customer verifies identity at Bank A, Bank B can reuse cryptographic attestations, cutting onboarding duplication. That reduces compliance cost and customer friction, though institutions must agree on revocation and revalidation policies. Teams implementing these solutions should map data sovereignty, set clear revocation workflows, and measure onboarding time and false-positive rates.
Permissioned Ledgers, Consortia And Interoperability
Fact first: banks prefer permissioned ledgers run by consortia to balance privacy with shared verification. That model scales governance and risk sharing.
Consortia let participants set membership rules, consensus thresholds, and privacy boundaries. For example, several regional banks formed a permissioned network for trade finance exchange and KYC sharing: that reduced duplicated compliance work across six institutions. Interoperability remains the trickiest part, connectors and standardized APIs translate assets and messages between ledgers and legacy systems. Interoperability frameworks now being trialed include atomic swaps, bridging contracts, and message-level translation layers.
Practically, institutes should join pilot consortia for shared services, require open API standards in vendor contracts, and run cross-ledger settlement drills. They should also plan governance: how to admit or remove members, upgrade contracts, and distribute operational costs. Failing to plan governance leads to gridlock when disputes arise, a lesson several early consortia learned the hard way.
Conclusion
Insight first: Blockchain beyond cryptocurrency is now about operational transformation, not hype. Banks that pair narrow pilots with clear metrics, settlement time, exception rates, and compliance cost, turn experiments into production. Firms should pilot tokenized cash rails, test custody integrations, and join permissioned consortia while documenting legal enforceability. Practical caution: interoperability and governance cause the most real-world friction: address them early or pilots stall. For teams building a roadmap, RarefiedTech’s resources on digital banking and security offer practical next steps and vendor comparisons.